Soft Decline vs. Hard Decline: How to Recover Failed Payments

Garry
November 18, 2026
1
minutes
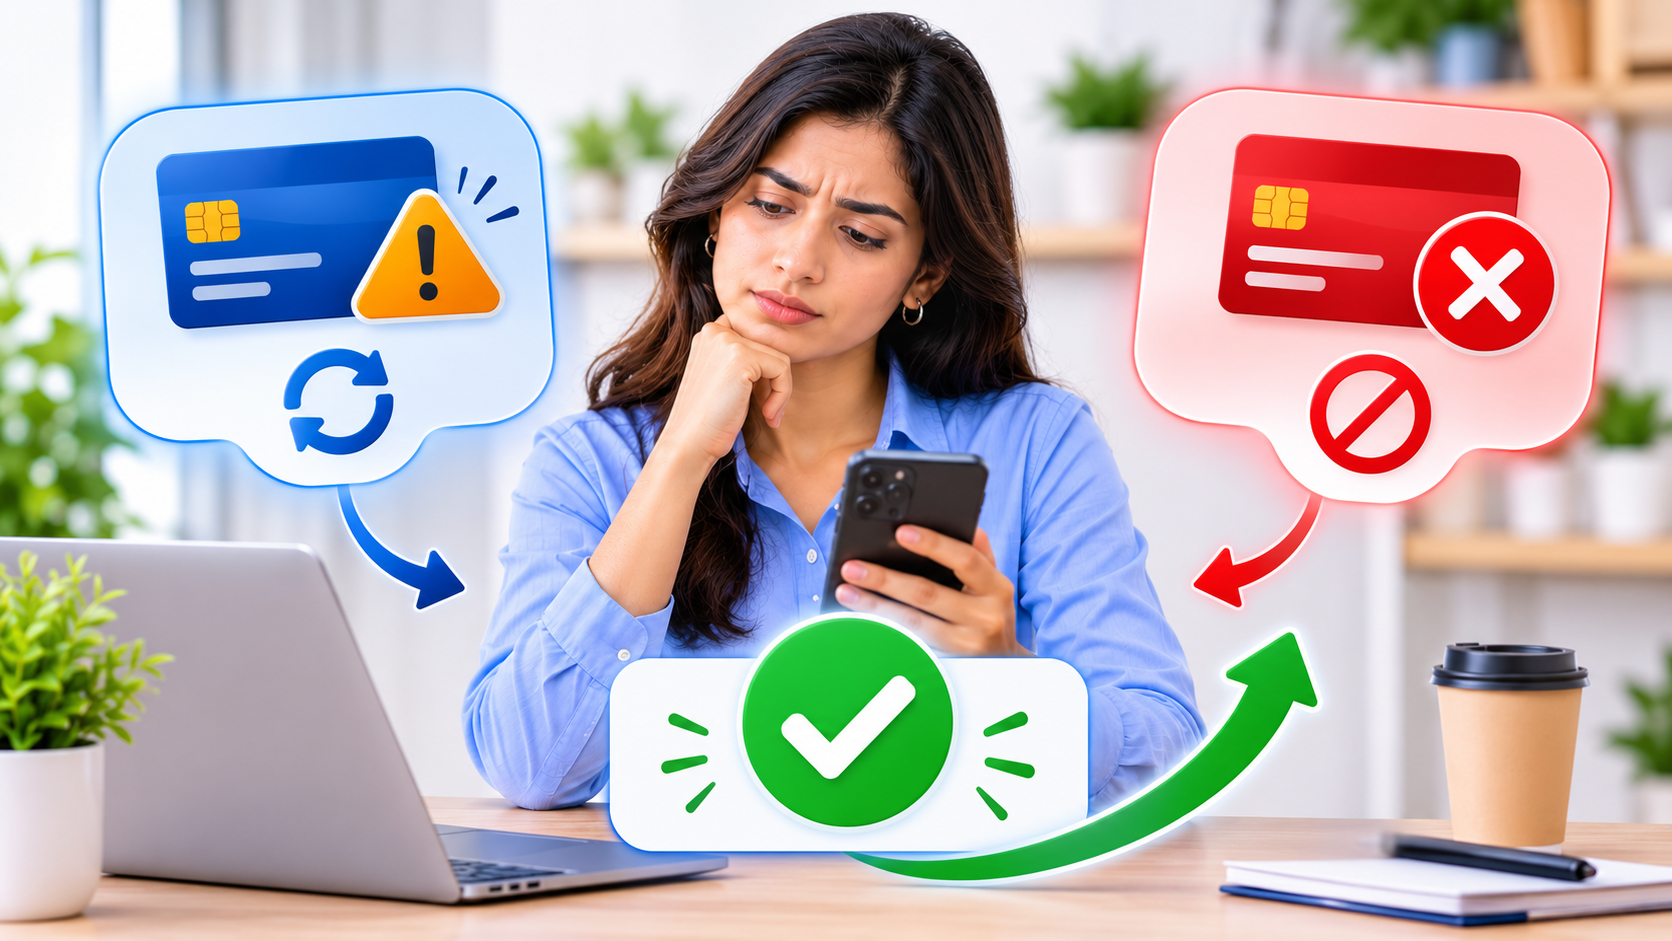
A customer finds what they want, adds it to their cart, enters their card details, and clicks “Pay.” But instead of a successful payment, the transaction is declined. The sale is suddenly at risk, even though the customer was ready to buy.
Many businesses treat a failed payment as a lost sale, but that is not always true. Some payments may go through if you try again later. Others should not be tried again because they will keep failing and may lead to extra fees.
These payment declines are of two types: soft declines and hard declines. A soft decline happens when the bank temporarily stops a payment due to reasons such as a spending limit or an extra security check. The payment may go through once the customer resolves the issue and tries again.
A hard decline usually means there is a serious problem with the card. It may be expired, closed, invalid, or reported as stolen. Trying the payment again will not fix the problem and could lead to additional fees from Visa and Mastercard.
Knowing the difference matters because the wrong approach can cost a business twice. It can lose customers whose payments could have been recovered and waste money retrying transactions that will never go through.
Understanding soft vs. hard payment declines helps businesses make better decisions about failed transactions. They can retry payments that have a chance of succeeding, avoid unnecessary fees, and recover more sales.
Keep reading to understand why these declines happen, when to retry a payment, and how to recover failed transactions.
What Is the Difference Between Soft and Hard Payment Declines?
When a customer pays by card, the payment processor sends a request to their bank for approval. The bank checks the card details, available funds, and transaction security. If it declines the payment, it also sends a code explaining why. The main difference is whether the payment can succeed if tried again:
A soft decline is usually temporary. For example, the customer may have reached a spending limit, need to complete a security check, or the bank may be facing a temporary technical issue. The payment may succeed if retried later or after the customer completes verification.
A hard decline means the card cannot be used for the payment. For example, it may have expired, been cancelled, or reported as stolen. Retrying will not help. The customer needs to use another valid payment method.
Some decline reasons do not fit neatly into either category. Always check the decline code to understand why the payment failed and decide what to do next.
What Causes a Soft Decline?
A soft decline does not always mean the customer's card has a problem. Sometimes, the bank blocks a payment because of a temporary issue that can be fixed. Here are some common reasons why soft declines happen:
Insufficient funds: The customer does not have enough money in their account or available credit to complete the payment.
Spending limits: The customer has reached their daily spending limit or the maximum number of card transactions allowed.
Incorrect card details: The customer enters the wrong CVV or billing address, causing the bank to reject the payment.
Security checks: The bank needs the customer to verify their identity through an extra step, such as 3D Secure.
Technical issues: A bank outage, network problem, or payment timeout prevents the transaction from going through.
Fraud checks: The bank or payment processor flags the transaction as unusual and blocks it for security reasons. Businesses can also explore fraud prevention tools to identify suspicious transactions and reduce unauthorised payment attempts.
If the same payment keeps failing, avoid repeated retries. Check the decline code and ask the customer to contact their bank or use another payment method.
What Causes a Hard Decline?
A hard decline means the bank will not approve the payment using the current card. Retrying the same payment will not solve the problem. Here are some common reasons:
Closed account: The customer has closed the bank account linked to the card, so the payment cannot go through.
Lost or stolen card: The customer has reported the card as lost or stolen, and the bank has blocked it.
Invalid card number: The card number is incorrect or does not exist, so the bank cannot process the payment.
Payment permission withdrawn: The customer has asked their bank to stop payments to your business. This often happens with recurring payments.
Blocked card: The bank has blocked the card, so it cannot be used for the transaction.
What about expired cards?
An expired card cannot be used for payments. The customer needs to provide updated card details before the payment can be processed. Instead of retrying, ask the customer to update their card information.
Retry Rules to Follow Before Recovering a Failed Payment
Visa and Mastercard have rules about how many times a business can retry a declined payment. If you ignore these rules, you may have to pay extra fees. Here are the rules that you can follow:
Visa retry rules: Visa does not allow retries for hard declines. For soft declines, retry limits apply. The exact limit may depend on the decline reason and current network rules, so check with your payment processor before trying again.
Mastercard retry rules: Mastercard also limits payment retries, but the rules depend on the decline code. Some declined payments can be retried, while others should not be retried.
Extra fees: Retrying payments too many times or retrying a hard decline can lead to additional fees. Mastercard may also investigate repeated misuse of its retry rules.
These rules and fees can change. Always check your payment processor's latest guidelines before setting up a retry schedule.
How to Recover Soft Declined Payments
A soft decline means the bank has temporarily stopped a payment. The payment may still go through once the problem is fixed. Here is what a business should do:
1. Find out why the payment failed: Check the decline code from the bank. It explains the reason for the failed payment and helps you decide the next step.
2. Take the right action based on the decline reason.
- Not enough money: Ask the customer to add money to their account before trying again.
- Spending limit reached: Wait until the bank resets the customer's spending limit.
- Technical issue: Try again once the bank or payment system is working.
- Security check required: Ask the customer to complete the bank's verification, such as 3D Secure.
3. Do not retry too many times: If the payment keeps failing, stop trying. Limit retries to three or four attempts, while following your payment processor's rules.
4. Try another payment processor: If the first processor has a technical problem, payment cascading to reduce failed transactions can send the transaction through another processor.
5. Contact the customer: If the payment still does not go through, explain why it failed and ask the customer to try another card or update their payment details.
What to Do After a Hard Decline
When a payment gets a hard decline, do not try the same card again. It will not work and may lead to extra fees. Instead, contact the customer and explain that their payment could not be completed.
Ask them to use another card or payment method, such as a bank transfer or digital wallet. You can also share a link where they can update their card details. Finally, save the reason for the decline in the customer's account so your team can track why the payment failed.
How FirmEU Can Help You Recover Failed Payments
Not every failed payment happens because of a problem with the customer's card. Sometimes, the payment provider may not support your type of business, or you may not have a backup provider if a payment fails. This can lead to more declined payments, especially for international and high-risk businesses that need reliable cross-border payment solutions.
FirmEU helps businesses find banks and payment providers that work with their type of business. It has a network of more than 250 institutions and connects businesses with suitable providers based on their industry, business type, and location. This makes it easier to find a payment partner without contacting different providers one by one.
Here is how we can help:
Find a suitable payment processor: The right provider can help reduce payment declines caused by an unsuitable payment setup.
Set up multiple payment routes: Working with more than one processor allows businesses to use payment cascading. If one processor cannot complete a payment, the transaction can be sent through another.
FirmEU is not a bank or payment processor. It connects businesses with providers, which handle account approval, payment processing, and retries. If your business is losing sales because of failed payments, we can help you find a payment partner that better fits your business needs.
Soft Vs. Hard Declines: Retry the Right Payments and Recover Revenue
Recovering failed payments starts with understanding why they were declined. Always check the decline code before taking action. Retry soft declines only after the problem has been resolved, and follow the payment network's retry rules. For hard declines, ask the customer to use another card instead of trying the same payment again. If a payment still fails, contact the customer and offer another way to pay.
Following these steps can help businesses recover more payments, avoid unnecessary fees, and lose fewer sales. FirmEU can also help businesses find payment providers that suit their industry and payment needs.
FAQs
What is the difference between a soft decline and a hard decline?
A soft decline means the bank has temporarily stopped the payment. This may happen because the customer has insufficient funds, has reached a spending limit, or needs to complete a security check. The payment may work if tried again later. A hard decline means the card cannot be used for the payment, such as when it is closed or reported as stolen.
Can you retry a hard-declined payment?
No. Trying the same payment again will not work and may lead to extra fees. Ask the customer to use another card or payment method.
How many times can you retry a soft-declined payment?
Three to four attempts are generally a good limit. However, Visa and Mastercard have their own retry rules. Check with your payment processor to make sure you follow the correct limits.
How long should you wait before retrying a failed payment?
It depends on why the payment failed. If the customer has reached a spending limit, wait around 24 hours. If they do not have enough money, try again when funds are available. If there is a technical issue, retry once it is fixed. If the bank needs extra verification, ask the customer to complete it first.
No. FirmEU is not a bank or financial institution. We operate as an independent matchmaking platform, connecting businesses with verified financial partners. All onboarding, KYC, and approval decisions are handled directly by the financial institution.
Still Have Questions?
Our sales team would be more than happy to assist with any futher inquiries
Contact Us
International Payment Solutions
Find the Right Banking and Payment Processing Partner for Your Business
Tell us about your company, and we’ll match you with the most suitable global banking or payment providers from our verified network.
Get Matched